How to manage storm and insurance roofing jobs without losing track
Storm work rewards the shops that stay organized. The roofing insurance claim process runs on evidence, dates, and written scope — not memory. A complete job file helps the contractor, homeowner, and carrier work from the same facts.
Here is a workflow a small shop can run from the first inspection to the final invoice.
1. Document the damage before it disappears
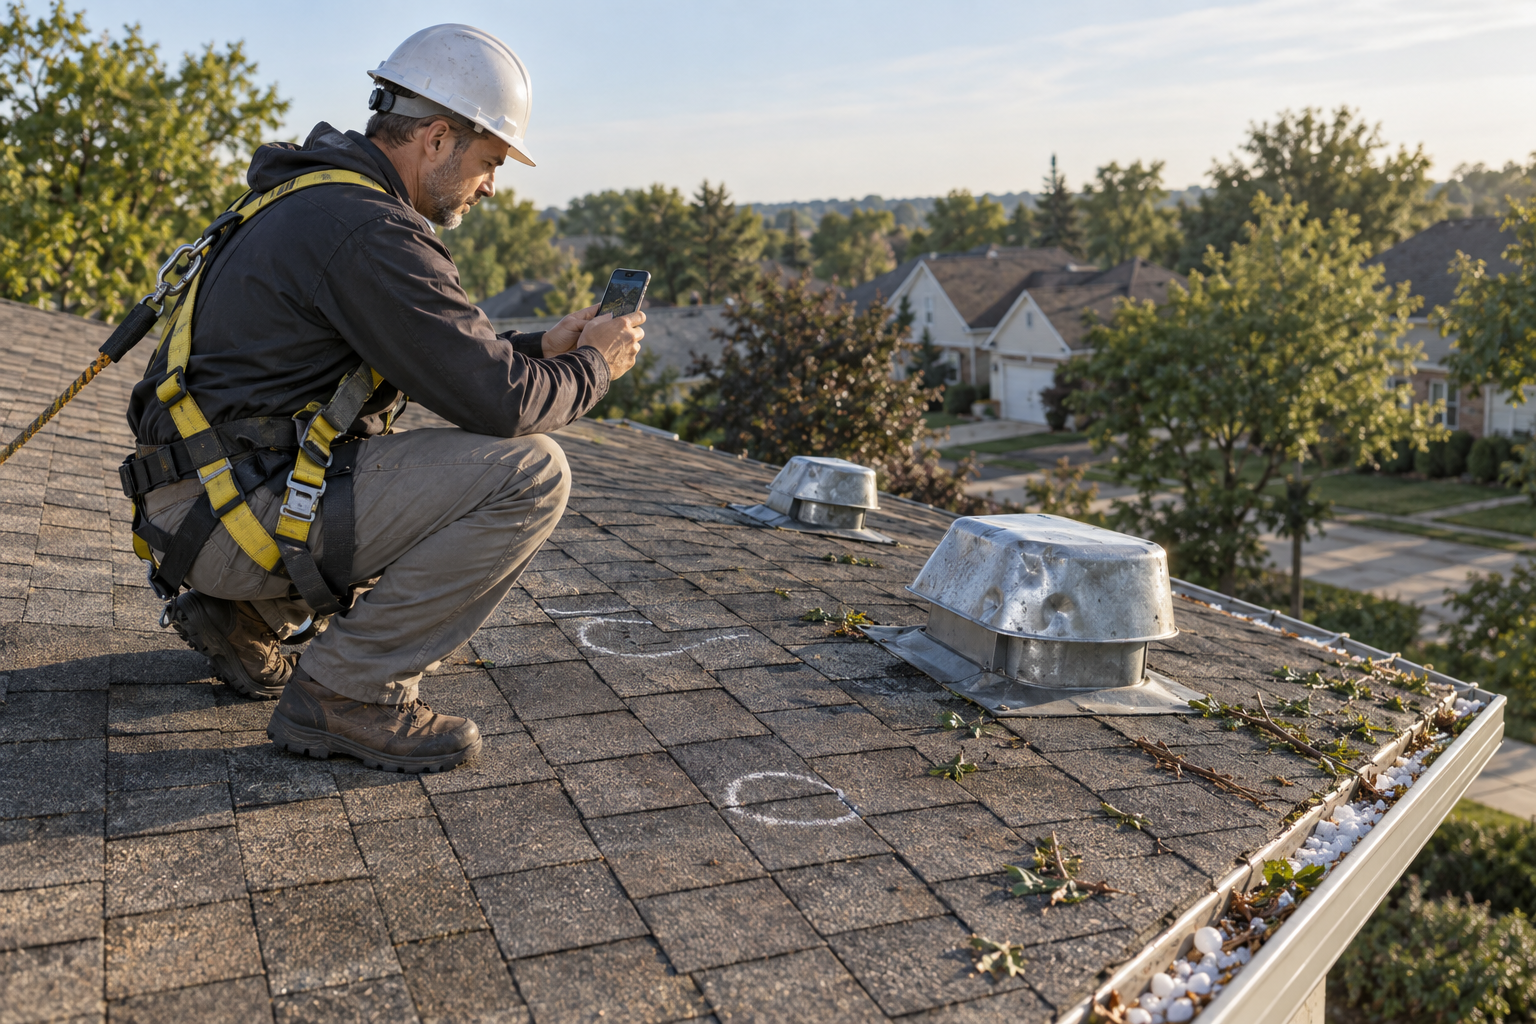
Once the old roof is off, the evidence is gone. On the first inspection, photograph everything: overview shots of each slope, close-ups of hail bruising or wind-lifted shingles, dented soft metals, flashing, vents, gutters, and any interior water intrusion. Date them, tie them to the address, and label them so a "damage" photo is never mixed in with a finished-job photo. Capture your own measurements too. This is the same evidence that supports the claim and, later, a supplement.
2. Keep the homeowner's claim theirs
The policyholder files the claim, not you. Help them understand the process, document what you found, and be present, but do not misrepresent damage or pressure a carrier. Your job is honest, thorough documentation of the roof; the homeowner owns the decision to file and the relationship with their insurer.
3. Meet the adjuster prepared
The carrier's adjuster inspects the property and documents the covered work in a scope or estimate. When the carrier and local rules allow the contractor to attend, arrive with organized photos, measurements, product details, and code documentation. Point out relevant conditions; do not try to direct the coverage decision.
4. Read the scope of work, then supplement with evidence
Review the carrier's scope against the roof and the contract. If it appears to omit covered work or conditions that were not visible before tear-off, the policyholder or an authorized party may be able to submit a supplement: a documented request for the carrier to reconsider the scope. The process and who may negotiate it vary by state. Every requested line should be supported by photos, measurements, code requirements, invoices, or other relevant evidence.
5. Never touch the deductible
Do not offer to waive, rebate, absorb, or "eat" a homeowner's deductible. That practice is illegal in states including Texas, and other states regulate it differently. Texas, for example, expressly prohibits contractors from waiving, rebating, or absorbing a property-policy deductible. (Texas Department of Insurance) State the homeowner's responsibility accurately in the contract and invoice, follow the law where you work, and ask a licensed attorney or state insurance regulator when the rule is unclear.
6. Run the job from one place, not five
Storm jobs fall apart in the handoffs — photos on one phone, the adjuster's name on a sticky note, the signed scope in an email, change orders in a text thread. Keep the inspection photos, the claim details, the scope, the crew's progress, and the documents together so nothing is lost between the inspection and the final walk. When the file is complete, the supplement is easier to justify and the homeowner sees a shop that has it handled.
7. Close out clean
Photograph the finished roof by slope, record the materials that were installed, reconcile every change order against the approved scope, and invoice the amount the contract and claim assign to the homeowner. A clean close-out supports payment, warranties, and future questions.
Rooferan keeps a storm job organized in one place. Capture and label damage photos on the roof (the photo-label catalog seeds a "Damage" label out of the box); store the claim number, adjuster name, and insurance company on the lead; keep insurance paperwork and correspondence on the job; track scope and change orders; and share customer-visible photos through a secure portal. Rooferan does not file your claims or write your supplements — it keeps the evidence and the workflow in order so you can. Some features and integrations vary by plan.